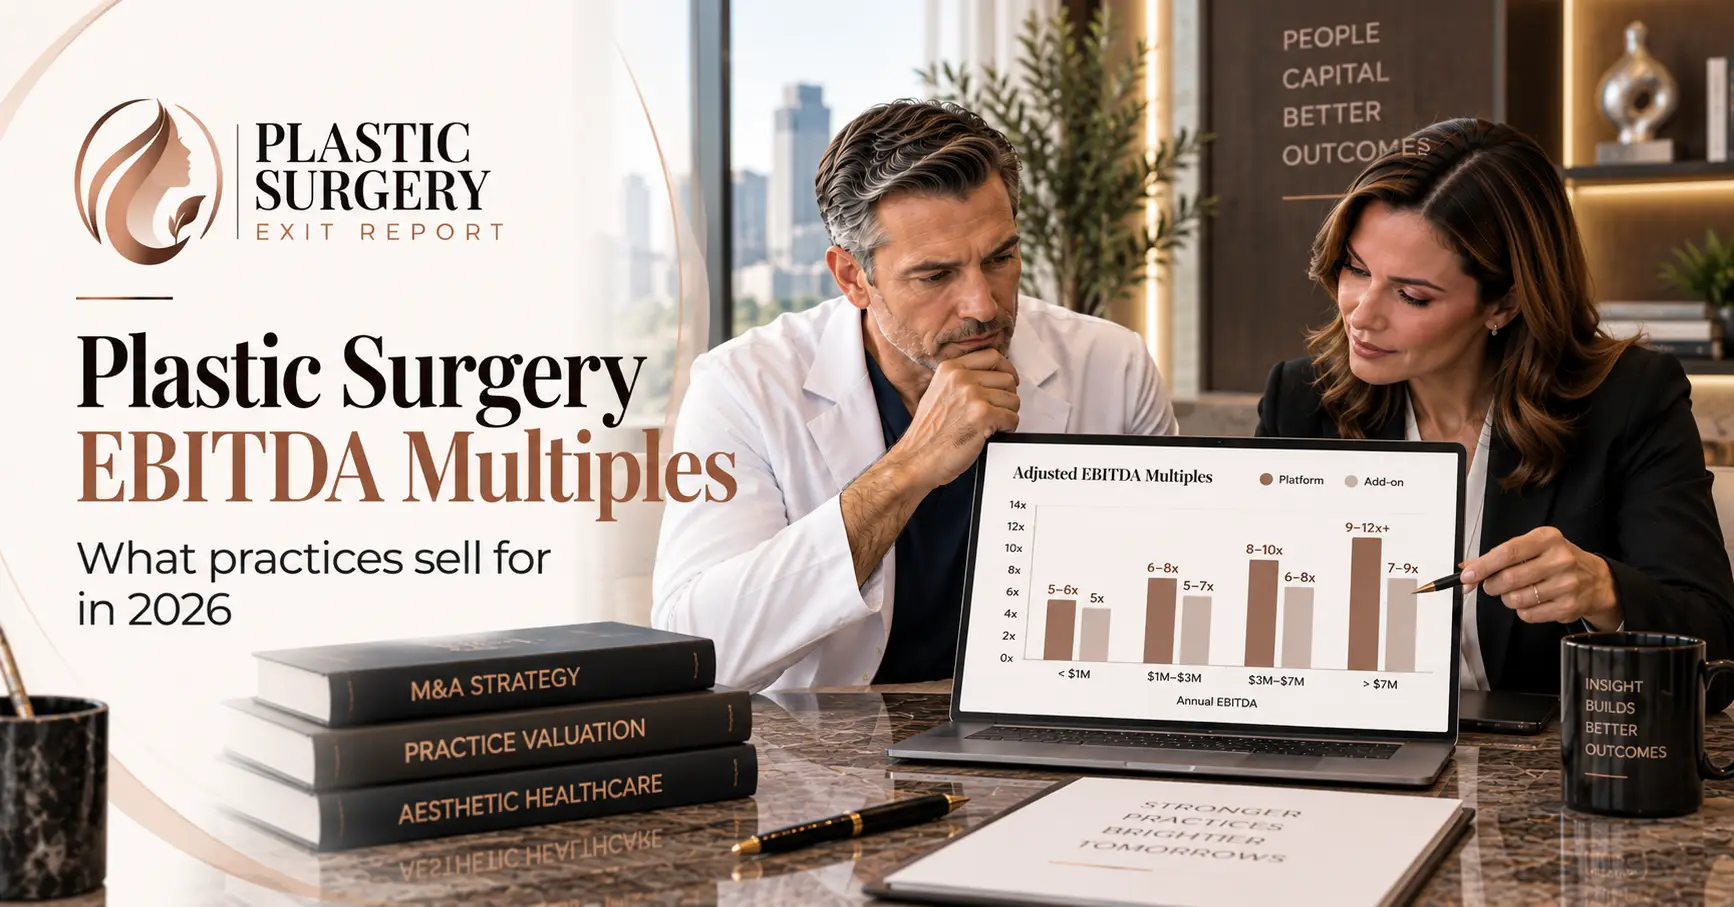
Plastic surgery practice EBITDA multiples are the shorthand everyone uses and few people explain. A buyer says “6x,” a colleague says his group got “10x,” and a broker’s website promises something in between. All of them may be right, because the multiple depends on how big the practice is, who’s buying, how earnings were calculated and how the deal is paid.
This guide sorts it out. It lays out the 2026 multiples reported by investment bankers, explains why they vary so much, shows how a single turn changes your outcome, and covers what you can do to earn a higher multiple. It builds on our main guide to plastic surgery practice valuation.
Key takeaways
- FOCUS Investment Banking reported 2026 plastic surgery platform deals from 5x to 6x EBITDA under $1 million up to 9x to 12x or more above $7 million, with add-ons at 5x to 9x (FOCUS).
- Size is the biggest driver. FOCUS calls $3 million of EBITDA a critical inflection point where multiples can rise by two to four turns.
- The multiple only means something alongside the EBITDA it’s applied to and the structure of the deal.
- Reducing dependence on one surgeon is the most reliable way to earn a higher multiple.
What multiple do plastic surgery practices sell for?
Most sell for a multiple of adjusted EBITDA that rises with size. FOCUS Investment Banking’s September 2026 benchmarks put platform acquisitions at 5x to 6x for practices under $1 million of EBITDA, 5x to 9x from $1 million to $3 million, 7x to 11x from $3 million to $7 million, and 9x to 12x or more above that.
Here is that data alongside a second FOCUS review:
| Adjusted EBITDA | Platform multiple | Source |
| Under $1 million | 5x to 6x | FOCUS, Sept 2026 |
| $1 million to $3 million | 5x to 9x | FOCUS, Sept 2026 |
| $3 million to $7 million | 7x to 11x | FOCUS, Sept 2026 |
| $7 million and above | 9x to 12x or more | FOCUS, Sept 2026 |
| Add-on acquisitions | 5x to 9x | FOCUS, Sept 2026 |
| Plastic surgery and aesthetics platforms | 8x to 12x | FOCUS, Apr 2026 |
| Plastic surgery and aesthetics add-ons | 4x to 8x | FOCUS, Apr 2026 |
The April review also noted that smaller, single-site aesthetics practices trade in the low to mid single digits, while multi-site platforms can reach high single to low double digits. Private practice deals aren’t public, so treat every range as a guide to your neighborhood, not a quote.
What is EBITDA, and why do buyers use it?
EBITDA is earnings before interest, taxes, depreciation and amortization. Buyers use it because it shows the cash a practice generates from operations, regardless of how it’s financed or taxed. For a practice sale, buyers use adjusted EBITDA, which removes owner-specific and one-time items and resets the surgeon’s pay to a post-sale level.
That adjustment is critical. The multiple is applied to adjusted EBITDA, so a small change in how earnings are recast can matter more than a full turn on the multiple. If you’re comparing offers, always ask what EBITDA figure each buyer used.
Why do plastic surgery practice EBITDA multiples vary so much?
Because buyers price risk and growth. Larger practices with several surgeons, recurring non-surgical revenue, an owned surgical facility and strong management carry less risk and more room to grow, so buyers pay more for each dollar of earnings. Deal structure, buyer type and how EBITDA was calculated also change the headline number.
The main reasons two practices with similar earnings get different multiples:
- Size and buyer pool. Bigger practices attract platform buyers, who pay more.
- Surgeon concentration. FOCUS lists single-surgeon concentration at 70% or more of revenue as a valuation detractor.
- Revenue mix. Recurring injectables and skin care make earnings steadier.
- Growth. Rising consultations and case volume support a premium. Flat volumes don’t.
- Facility ownership. An accredited, owned facility adds revenue and control.
- Structure. A higher headline multiple paid largely in rollover equity or earnouts can be worth less than a lower all-cash multiple.
Platform vs add-on multiples: what’s the difference?
A platform is the first practice a private equity firm buys to build around, so it commands the highest multiple. An add-on is a practice bought to join an existing platform, usually at a lower multiple. FOCUS reported 2026 add-on deals at 5x to 9x, with platform multiples reaching 9x to 12x or more for the largest practices.
The gap exists for a reason. A platform buyer is paying for leadership, infrastructure and a base to grow from. An add-on buyer already has those things and is buying patients, surgeons and geography. Most independent practices sell as add-ons, which is why it’s worth knowing whether a buyer sees you as one or the other.
What is multiple arbitrage, and why does it matter to you?
Multiple arbitrage is the gap between the lower multiples platforms pay for add-ons and the higher multiple they hope to receive when they sell the combined, larger business. It’s a core part of the private equity model, and it’s why rollover equity in a growing platform can be valuable.
Here’s a hypothetical illustration, with figures for explanation only. A platform buys several practices at an average of 6x EBITDA. The combined group, now much larger, later sells at 10x. Every dollar of earnings bought at 6x is now valued at 10x. If you rolled equity into that platform, you share in that gain. If you sold all-cash at 6x, you don’t. Our guide to the second bite of the apple in plastic surgery explains how that payout works.
How much is one turn of EBITDA worth?
One turn equals one year of adjusted EBITDA. For a practice with $1.5 million of adjusted EBITDA, moving from 6x to 7x adds $1.5 million to the enterprise value. That’s why small improvements in risk, like adding a second surgeon, can be worth far more than their cost.
A hypothetical comparison, for illustration only:
| Adjusted EBITDA | At 5x | At 6x | At 7x | At 8x |
| $750,000 | $3.75M | $4.5M | $5.25M | $6.0M |
| $1,500,000 | $7.5M | $9.0M | $10.5M | $12.0M |
| $3,000,000 | $15.0M | $18.0M | $21.0M | $24.0M |
Now combine the two levers. Growing EBITDA from $1.5 million to $3 million doubles earnings, and moving past the $3 million threshold may also lift the multiple. That combined effect is why growth before a sale matters so much.
How do buyers apply plastic surgery practice EBITDA multiples to your numbers?
They recast your earnings first, then apply a multiple that reflects your risk, then adjust for debt, working capital and structure. The result is the enterprise value, which isn’t the same as the cash you receive. Understanding each step helps you see where an offer came from.
A simplified sequence, with hypothetical figures:
- Reported EBITDA: $900,000.
- Recast: add back $150,000 of personal and one-time expenses, adjust surgeon pay to the post-sale formula (+$400,000) and reset rent to market (-$100,000). Adjusted EBITDA becomes $1,350,000.
- Multiple: the buyer applies 6.5x, reflecting a single-site practice with one associate. Enterprise value is about $8.8 million.
- Structure: perhaps 75% cash at closing and 25% rollover equity, with any debt paid off and a working capital target set.
Every line is negotiable. Plastic surgery practice EBITDA multiples get the attention, but steps two and four often move your outcome just as much.
Are plastic surgery practice EBITDA multiples rising or falling?
Nobody can promise where multiples will go. What the 2026 data shows is active demand: FOCUS reported a broad range of platform and add-on pricing, and Physician Growth Partners counts ten or more PE-backed plastic surgery platforms competing for practices. Borrowing costs, patient demand and regulation can all shift pricing, so base decisions on current offers, not headlines.
How do plastic surgery multiples compare with other physician specialties?
They’re broadly in line with other physician practices, with a premium possible for cash-pay, multi-site groups. FOCUS’s 2026 review of physician practice multiples put practices under $1 million of EBITDA at 5x to 7x and those above $5 million at 11x to 13x, similar to the plastic surgery ranges.
Plastic surgery has distinctive features that cut both ways. Cash-pay revenue avoids insurance reimbursement risk, which buyers like. But cosmetic procedures are discretionary, so buyers test how your numbers would hold up in a slower economy. And personal goodwill tends to be large, because patients choose a surgeon, which is why employment agreements and non-competes are standard.
How does an owned surgical facility affect your multiple?
It usually helps. FOCUS lists facility ownership, including accredited suites and owned surgery centers, among the factors that command premiums. A facility adds its own revenue and gives the buyer operating control. For context, VMG Health notes many ambulatory surgery centers trade around a historical benchmark of 7x to 8x EBITDA.
Facility value depends on case volume, accreditation history, equipment and who uses the space. Our guide to surgery center valuation covers how buyers price an owned surgical suite in detail, including what happens to the real estate.
How can you earn a higher multiple?
Reduce dependence on yourself, grow steadily, add recurring non-surgical revenue, keep clean financials, strengthen management, fix compliance gaps and run a competitive process. The first lowers perceived risk, the next few raise earnings quality, and competition makes buyers pay for both.
A practical priority list:
- Hire or develop an associate surgeon with their own caseload.
- Grow injectables and skin care into a meaningful share of revenue.
- Keep monthly accrual financials with revenue by surgeon and service.
- Document every add-back, and consider a sell-side quality of earnings review.
- Build a practice brand that doesn’t rely only on your name.
- Put several qualified buyers in competition. Our guide to who buys plastic surgery practices explains who to include.
Frequently asked questions
What EBITDA multiple do plastic surgery practices sell for?
It depends on size and buyer. FOCUS Investment Banking reported 2026 platform deals at 5x to 6x EBITDA under $1 million, rising to 9x to 12x or more above $7 million, with add-ons at 5x to 9x. Surgeon concentration, growth, revenue mix and facility ownership decide where a practice lands.
Why did a colleague get a higher multiple than my offer?
Probably because of size, surgeon depth, growth or structure. Larger multi-surgeon practices attract platform buyers who pay more. A higher headline multiple may also include more rollover equity or earnouts, or be applied to a different EBITDA figure. Compare cash at closing and the EBITDA used, not just the multiple.
Is a higher multiple always a better deal?
No. A higher multiple applied to lower adjusted EBITDA, or paid mostly in rollover equity and earnouts, can leave you with less than a lower multiple paid mostly in cash. Compare total value, guaranteed cash, the risk in any equity and your post-sale compensation before choosing.
What is the $3 million EBITDA threshold?
FOCUS Investment Banking describes $3 million of EBITDA as a critical inflection point where the buyer pool shifts from local add-on buyers to platform-ready buyers, and multiples can increase by two to four turns. Growing past it, often by adding surgeons or locations, can significantly raise value.
Do plastic surgery practices sell on revenue multiples?
Rarely as the main method. Revenue multiples ignore margins and owner compensation, which vary widely between practices. Buyers use adjusted EBITDA and apply a multiple, then adjust for risk and structure. A revenue multiple may appear as a rough check, but it shouldn’t drive your expectations.
How can I increase my practice’s EBITDA multiple?
Add surgeon capacity so the practice doesn’t depend on you, grow recurring non-surgical revenue, keep clean financials, document add-backs, strengthen management and run a competitive sale process. FOCUS lists revenue diversification, multi-provider depth, ancillary revenue and facility ownership among the drivers of premium valuations.
Plastic surgery practice EBITDA multiples: the bottom line
Plastic surgery practice EBITDA multiples in 2026 range from mid single digits for smaller practices to low double digits for large platforms. The multiple you get depends on size, risk, growth and structure, and it only means something alongside the EBITDA it’s applied to. Improve both, then let competition set the price.
| Want to know where your practice would land? Get the Plastic Surgery Exit Report newsletter for quarterly valuation data, or book a confidential conversation with the plastic surgery team at Olympic M&A. Disclosure: Plastic Surgery Exit Report is published in partnership with Olympic M&A, a healthcare M&A advisory firm. |